
Where Does Your Money Actually Go Each Month?
Understanding the difference between fixed, variable, and discretionary expenses is the first step to building a budget that works.
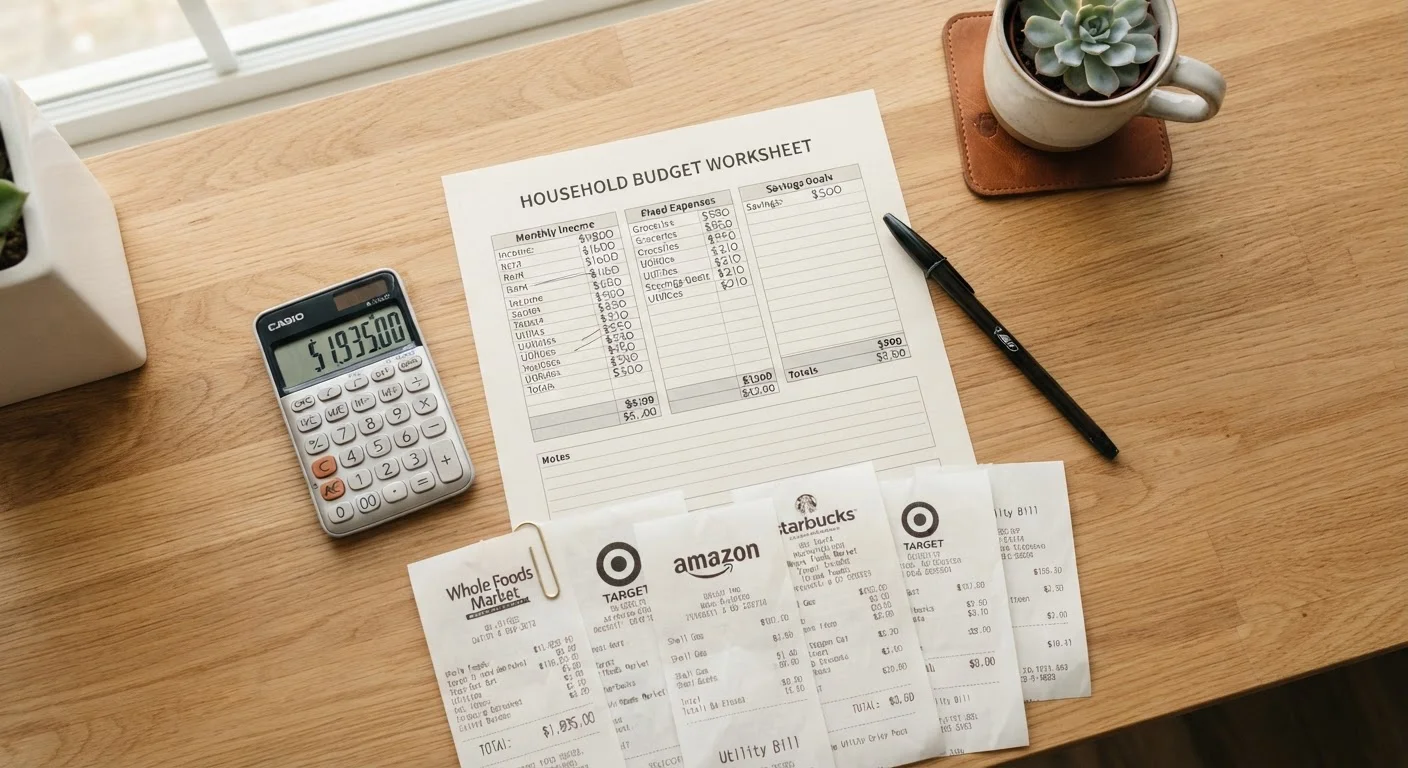
Photo: HorizonMetric.com | One Destination For Everyday Insights editorial
—— In This Article
Key Takeaways
- Fixed expenses are predictable costs you pay every month, like rent and loan payments.
- Variable expenses shift month to month and are often the easiest place to find savings.
- Discretionary spending covers wants and lifestyle choices — not bare necessities.
- Tracking all three expense types before budgeting is essential for accuracy.
- Your budget should be built on net (take-home) income, not gross pay.
The Three Types of Monthly Expenses
Most Americans who feel like they're losing track of their money aren't overspending in one dramatic way — they're losing small amounts across many categories they haven't clearly defined. The fix starts with understanding the three types of expenses.
Fixed expenses are consistent charges you pay every month in the same amount. Think rent or mortgage, car loan payments, insurance premiums, and minimum debt payments. These are largely non-negotiable on a month-to-month basis, which makes them the easiest to plan around.
Variable expenses are necessary but fluctuating costs. Groceries, gas, electricity, and medical co-pays fall here. You can't eliminate them, but the amount you spend shifts depending on behavior, season, and circumstance. This is often where significant savings opportunities hide.
Discretionary expenses are choices rather than necessities — dining out, subscriptions, hobbies, travel, and clothing beyond basics. They're a normal and healthy part of life, but they're the category most people underestimate when trying to understand why their paycheck disappears before the month ends.
This Is General Financial Education
The framework described here — fixed, variable, and discretionary expenses — is a widely used educational model for personal budgeting. It is general information, not personalized financial advice. Every household's circumstances differ, and a licensed financial professional can help you apply these concepts to your specific situation.
Why Tracking Comes Before Budgeting
Many people try to build a budget before they understand their actual spending habits, which is like drawing a map of a place you've never visited. Tracking first gives you real data to work with.
Spend one month — ideally three — collecting every transaction from your bank account and credit cards. Sort each charge into fixed, variable, or discretionary. You'll often find expenses you'd forgotten entirely: auto-renewing subscriptions, annual fees billed monthly, or small daily purchases that compound into hundreds of dollars.
Before you track spending, make sure you're working from the right income figure. Understanding the difference between net and gross income is a critical first step — budgeting from gross pay can make your plan look feasible on paper while leaving you short every month.
33%
Americans with no monthly budget
According to a survey by the National Foundation for Credit Counseling, roughly one in three Americans does not maintain a household budget.
$1,000+
Average annual untracked discretionary spend
Consumer spending research consistently shows households underestimate discretionary costs by hundreds to over a thousand dollars annually when relying on memory rather than records.
Finding the Leaks in Your Budget
Once you've mapped your spending, patterns become visible. Most households find their variable and discretionary categories are significantly higher than they estimated — sometimes by 20 to 40 percent.
Variable expenses like groceries are especially tricky. A household might estimate $400 per month and actually spend $580, not because of poor discipline but because of price changes, household fluctuations, and unplanned meals. The same dynamic plays out with gas, utilities, and personal care.
Discretionary spending often surprises people most. Individually, a $14 streaming service or a $6 coffee feels negligible. Collectively, several of these small recurring costs can total $200 to $400 or more each month.
After reviewing three months of actual data, use a checklist to audit what you find. The monthly budget audit checklist is a structured way to review your cash flow, spot overlooked charges, and realign your spending with your actual goals.
Use Real Numbers, Not Round Estimates
When building your expense categories, pull actual figures from your statements rather than guessing. Round estimates consistently understate spending. Even being off by $50 across five categories adds up to a $3,000 annual gap between your budget and reality.
Building a Budget That Reflects Real Life
A budget that ignores irregular expenses will fail. Annual costs like car registration, holiday gifts, or back-to-school supplies need to be divided across 12 months and treated as monthly line items — otherwise they'll blow your budget every time they appear.
If your income changes month to month, standard budgeting rules need adjustment. Budgeting strategies for variable income earners can help gig workers and the self-employed plan around income that isn't predictable.
A realistic budget also includes a small buffer — sometimes called a miscellaneous or buffer category — to absorb the unexpected without derailing the whole plan. Even $50 to $100 set aside monthly for unanticipated costs can mean the difference between a budget that bends and one that breaks.
This article is for general informational and educational purposes only and does not constitute personalized financial advice. Consult a licensed financial professional for guidance specific to your situation.
Frequently Asked Questions

Finance Editorial Team
Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile