
Why Travelers Overspend—and the Habits That Keep Budgets on Track
Common spending patterns that derail travel budgets, with practical habits to stay financially on track without sacrificing the experience.
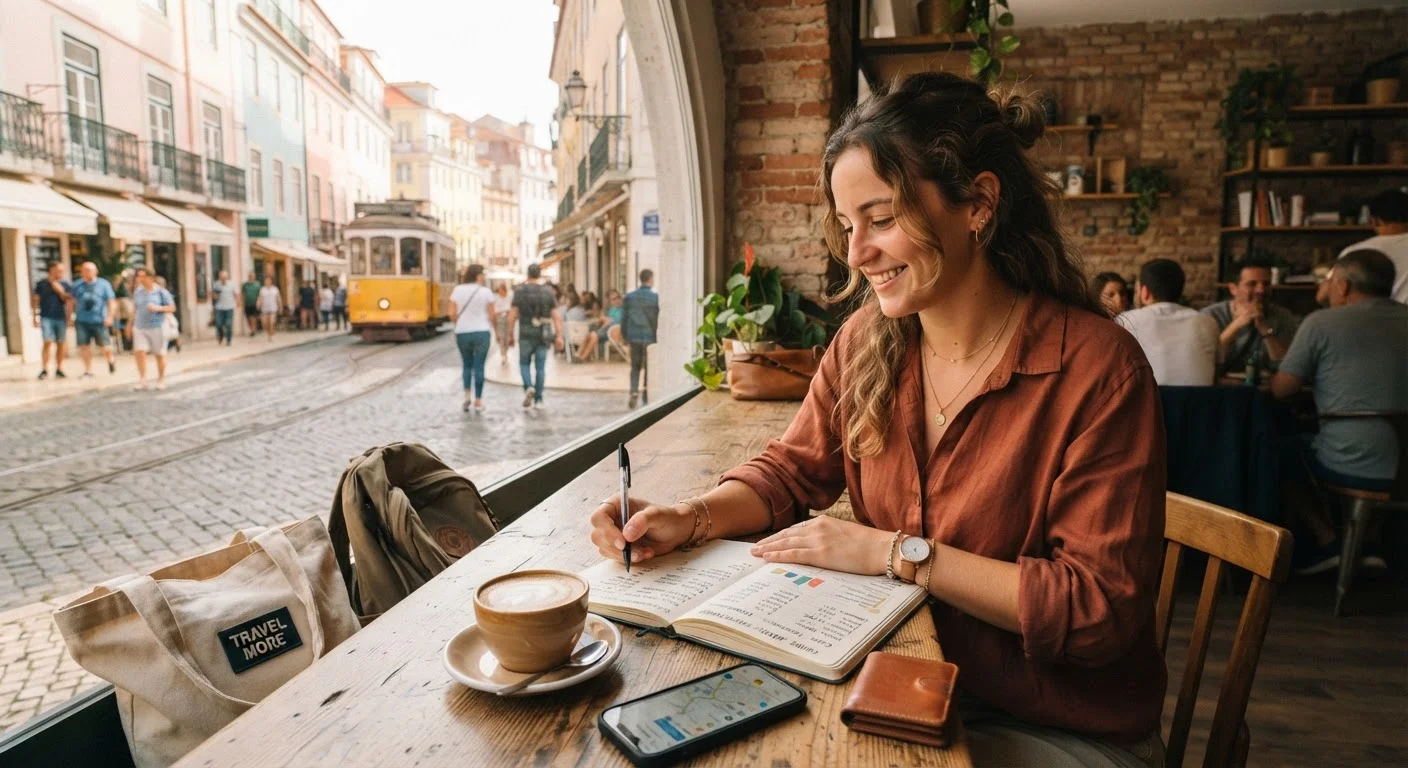
Photo: HorizonMetric.com | One Destination For Everyday Insights editorial
Key Takeaways
- Most travel overspending traces back to planning gaps, not poor self-control on the road.
- Building a contingency buffer of 10–15% into your budget prevents minor surprises from becoming financial stress.
- Tracking spending daily during a trip—even briefly—keeps small costs from accumulating invisibly.
- Underestimating "in-between" costs like airport meals and transit fees is one of the most common budget killers.
- A clear daily spending limit, set before departure, gives travelers freedom without the post-trip regret.
The Real Reason Travel Budgets Fall Apart
Most travelers don't overspend because they're reckless — they overspend because their budget was incomplete before they ever booked a flight. A plan that covers airfare and hotels but ignores airport transfers, dining beyond the hotel, activity entrance fees, and tipping customs is a plan built on optimism, not reality.
The good news: overspending on trips is almost always preventable with a few structural changes to how you plan. Understanding why budgets crack under pressure is the first step. For a comprehensive look at where money quietly disappears, see our breakdown of every travel cost category that travelers routinely overlook.
Building a budget around "big ticket" items only, ignoring small daily costs.
Why it happens: Flights and hotels are the most visible expenses, so travelers focus their planning energy there. Costs like coffee, transit, snacks, and admission fees feel small individually and go untracked.
Skipping a contingency fund because the base budget already feels tight.
Why it happens: When money is stretched, adding a buffer feels counterintuitive. Travelers assume they'll manage surprises as they come, which often means putting unplanned costs on a credit card.
Relying on memory instead of real-time tracking during the trip.
Why it happens: Tracking spending while traveling feels like homework — travelers are there to enjoy themselves, not audit receipts. Small purchases feel forgettable in the moment.
Ignoring the cost of travel days — airports, transit hubs, and arrival logistics.
Why it happens: Travel days feel like "in between" time rather than real trip days, so they're left out of daily budgets. Airport meals, baggage fees, and taxi or rideshare costs from the airport add up faster than anticipated.
Letting "vacation mode" override spending decisions without a daily anchor.
Why it happens: Travel carries a psychological permission slip to spend more freely. The mental framing of "I'm on vacation" lowers the resistance that normally applies to discretionary purchases.
Habits That Actually Keep You on Track
Avoiding these mistakes is only half the equation. Building consistent habits before and during your trip is what separates travelers who come home financially relaxed from those who dread opening their bank statement.
~30%
Travelers who exceed their trip budget
Surveys from travel research organizations consistently find that roughly one in three leisure travelers spends more than they planned, with underestimated daily costs cited most often as the cause.
10–15%
Recommended contingency buffer
Travel financial planning resources commonly suggest reserving 10–15% of total trip costs as a contingency to absorb unexpected expenses without derailing the trip.
Set a daily spending limit — and write it down. Before departure, divide your total discretionary budget (food, activities, shopping) by the number of trip days. That daily figure becomes your anchor. When you hit it, you pause and prioritize rather than continuing to swipe.
Check in nightly. Spending five minutes each evening reviewing that day's purchases — using a notes app, a small journal, or a dedicated budgeting tool — is one of the highest-impact habits a traveler can develop. For ideas on which tracking format suits your style, explore the trade-offs between paper, spreadsheets, and apps.
Build a buffer and treat it as off-limits. A contingency of 10–15% of your total trip budget — kept mentally separate from your spending money — absorbs the unexpected without derailing the rest of the trip. Flight change fees, a medical co-pay, a last-minute museum you didn't plan for: these are routine, not emergencies.
Credit Cards Are Not a Budget Safety Net
Putting unplanned trip expenses on a credit card and planning to "figure it out later" is one of the most common ways a vacation creates lasting financial stress. Interest charges on a balance carried for several months can meaningfully increase the real cost of the trip. If you find yourself regularly relying on credit to cover travel surprises, that's a signal to revisit how your budget is structured — not just while traveling, but in everyday spending as well. Budgeting basics can help you build stronger financial habits overall.
Finally, it helps to recognize that the same patterns that hurt everyday household budgets also undermine travel finances. Understanding structural budget mistakes in your regular life often reveals exactly why trips go over, too.
Travel Editorial Team
Travel Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile