
Monthly Budget Audit: A Checklist for Finding Money to Save or Apply to Debt
A practical checklist to review your monthly cash flow, spot overlooked expenses, and redirect funds toward savings or debt repayment.
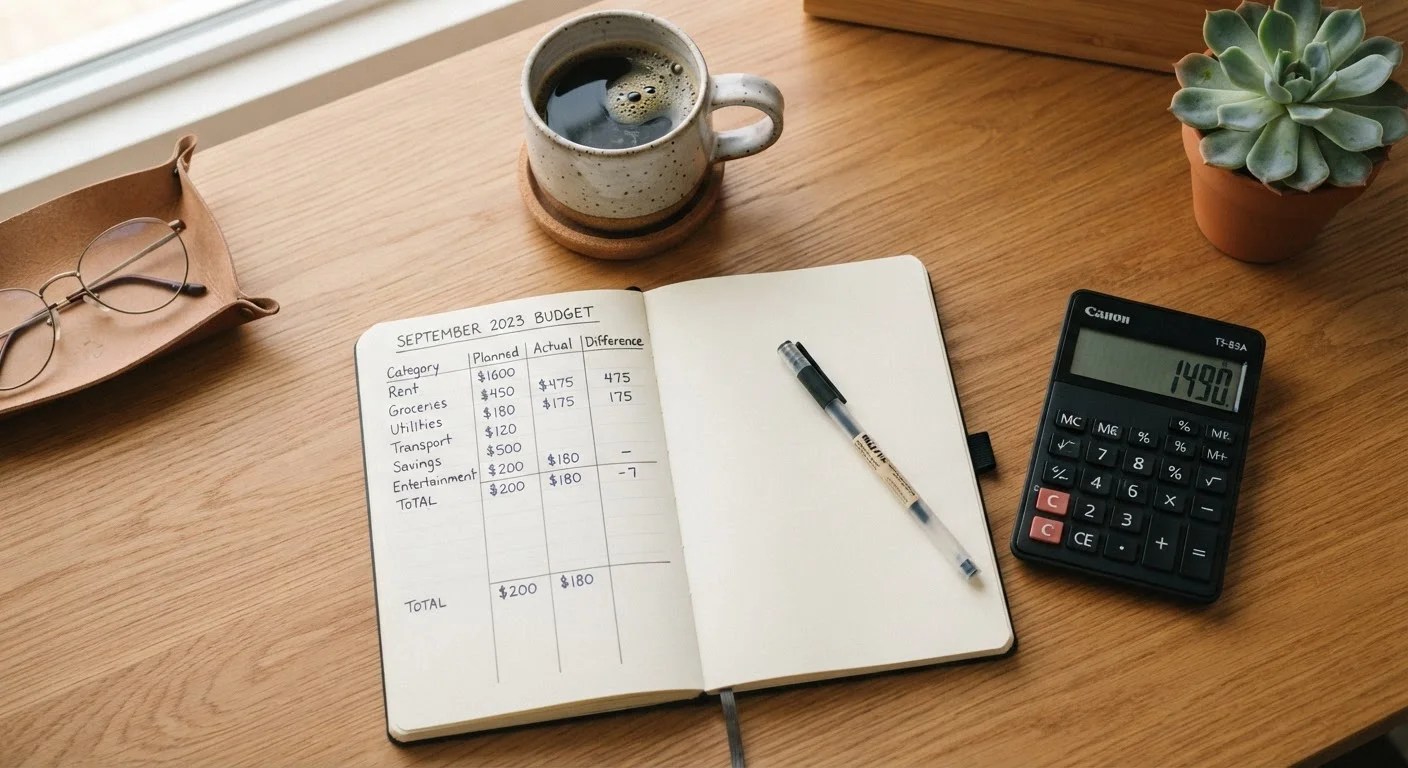
Photo: HorizonMetric.com | One Destination For Everyday Insights editorial
—— In This Article
Key Takeaways
- A monthly budget audit helps you spot spending leaks before they compound over the year.
- Canceled or renegotiated subscriptions and services often yield the fastest savings.
- Any found money should be immediately directed to a specific goal—savings or debt—before it disappears.
- Debt repayment and saving can coexist; prioritization depends on interest rates and your emergency cushion.
- Consistency matters more than perfection—a brief monthly review builds lasting financial habits.
Why a Monthly Audit Beats Annual Budgeting
Most people set a budget once and revisit it only when something goes wrong. The problem is that expenses drift quietly. A streaming plan upgrades itself, an annual insurance renewal creeps up, a gym membership goes unused for six months—and none of it registers until the bank balance looks thinner than expected.
A monthly audit is a short, structured review—typically 30 to 60 minutes—where you compare what you planned to spend against what you actually spent, then look deliberately for money that could be redirected. Think of it as a financial check-up rather than a punishment. If you're new to building a spending plan entirely, start with the fundamentals of personal budgeting before running this audit.
Use the checklist below in any order that suits your accounts. Work through one category at a time, and keep a running tally of anything you find to cut, reduce, or reallocate.
Bank and Credit Card Statements
Provide the complete transaction history needed to compare planned versus actual spending for the month.
Spreadsheet or Budgeting App
Tracks categories, running totals, and month-over-month trends so patterns become visible over time.
Debt Account Statements
Shows current balances, minimum payments, and interest rates needed for the debt snapshot section.
Subscription Tracking Tool or Manual List
Helps surface every recurring charge in one place so nothing slips through unnoticed.
The Monthly Budget Audit Checklist
Work through each group below using your bank statements, credit card statements, and any budgeting app you rely on. Flag every item where actual spending differs from your expectation—either over or under.
Gather Your Data
Fixed Expenses Review
Subscriptions and Recurring Services
Variable Spending Review
Debt Snapshot
Savings and Goal Progress
Audit Results Need a Clear Next Step
Finding a spending leak is only half the work. Every item you cut or reduce must be explicitly redirected—either to a debt account or a savings goal—before the next billing cycle begins. Without a specific destination, the freed-up funds typically re-enter discretionary spending without you noticing. Write down exactly where each dollar is going after this audit.
If you consistently have money left over after this audit but still carry high-interest debt, read about when saving alongside debt makes sense to decide where found money belongs first.
Putting Found Money to Work
The audit only delivers results if you act on what you find. For every dollar you free up, assign it immediately to one of two purposes before the month closes:
- High-interest debt (generally above 7–8% APR): Extra payments reduce the interest you pay over time, often faster than a savings account can earn.
- Savings goals: An emergency fund covering three to six months of essential expenses is a widely cited target, though the right amount depends on your income stability and household situation.
For irregular but predictable costs—car registration, holiday gifts, annual subscriptions—consider building sinking funds to handle them without stress. Setting aside a small amount monthly prevents these bills from blowing up your budget when they arrive.
Don't Let Found Money Sit Idle
When you identify savings through this audit, transfer or apply those funds within 24–48 hours. Money left in a checking account tends to get absorbed by ordinary spending before it reaches its intended purpose. Automation—such as scheduling a one-time extra debt payment or a transfer to a savings account—removes the decision entirely.
If your income varies month to month, the audit still applies—but your baseline numbers will shift. Irregular income budgeting strategies can help you build a floor before running this process. For a broader look at everyday budget categories, the Budgeting Basics hub offers additional tools and frameworks.
This article is for general informational purposes only and does not constitute personalized financial, tax, or investment advice. Consult a qualified financial professional for guidance specific to your situation.

Finance Editorial Team
Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile