
How Sinking Funds Work — and Why They Reduce Financial Stress
Irregular but predictable expenses wreck many budgets. Sinking funds are a simple mechanism for handling them without panic.
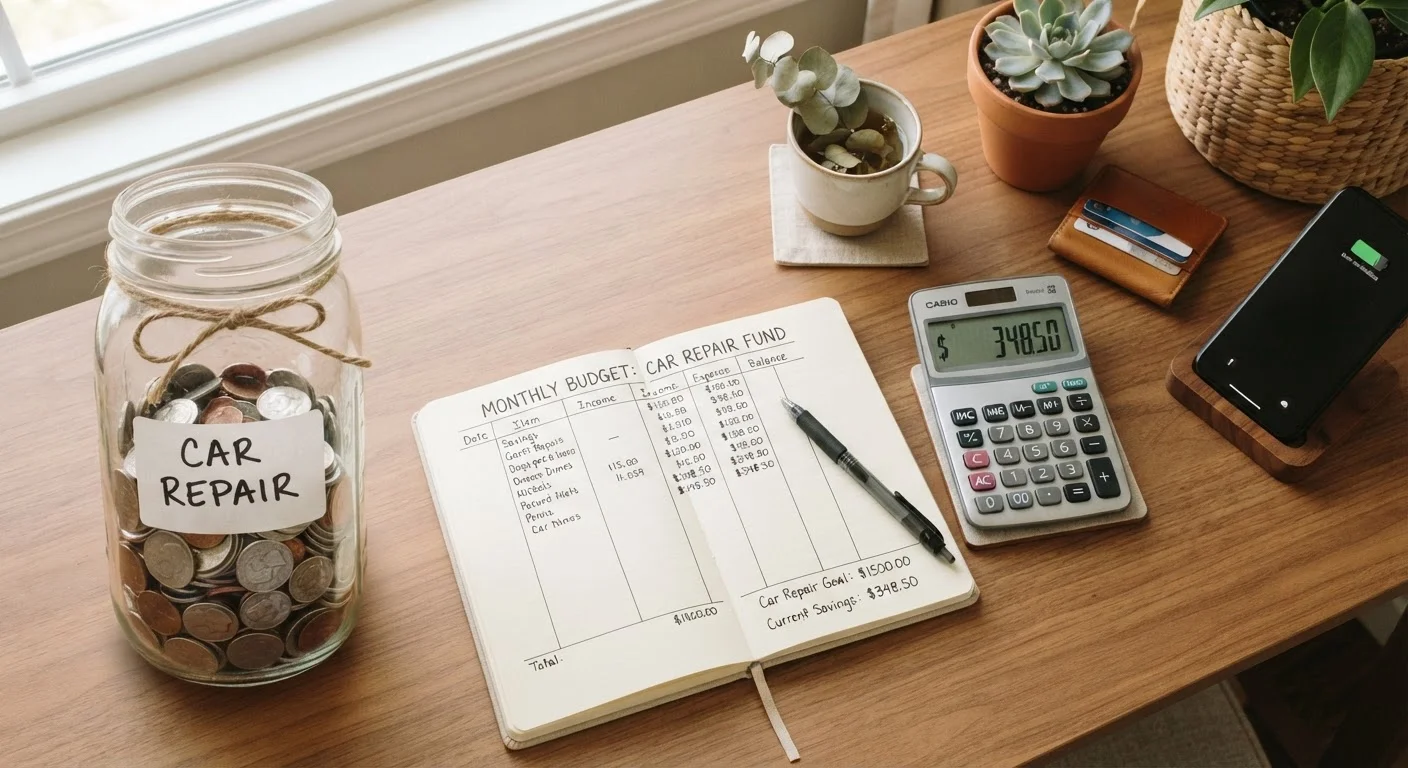
Photo: HorizonMetric.com | One Destination For Everyday Insights editorial
—— In This Article
Key Takeaways
- Sinking funds break large, predictable expenses into manageable monthly contributions.
- They are separate from emergency funds, which cover unexpected, unplanned costs.
- Common uses include car maintenance, annual insurance premiums, vacations, and holiday gifts.
- Setting up multiple category-specific funds reduces financial anxiety around irregular bills.
- Even small monthly contributions, started early enough, can fully cover major expenses.
Why Irregular Expenses Break Budgets
Most Americans budget around predictable costs — rent, groceries, utilities, streaming subscriptions. But budgets routinely collapse not because of those monthly line items, but because of the costs that arrive less frequently: car repairs, dental work, holiday shopping, annual insurance renewals, back-to-school expenses. These bills are irregular, but almost never truly unexpected.
If you've ever thought "my budget was fine until..." followed by a car registration, a vet bill, or a birthday trip, you've experienced this gap firsthand. The problem isn't that you overspend on essentials — it's that your budget isn't built to absorb costs that don't arrive every 30 days. That's exactly the problem sinking funds solve.
Understanding why budgets fail is the first step to building one that holds up through the whole year.
40%
Americans who can't cover a $400 emergency
According to Federal Reserve surveys, a significant share of U.S. households report they would struggle to cover a $400 unexpected expense without borrowing or selling something.
~$1,500
Average U.S. holiday spending per household
National Retail Federation data shows average household holiday spending routinely exceeds $1,000, making it one of the most budget-disrupting annual events.
$500–$700
Average annual car maintenance cost per vehicle
Industry estimates from AAA and similar organizations place routine vehicle maintenance costs in this range, not including major unplanned repairs.
How to Build and Use a Sinking Fund
The mechanics are straightforward. Start by listing every expense you can reasonably anticipate over the next 12 months that doesn't come out of your regular monthly budget. Common categories include:
- Car maintenance and registration
- Home repairs (HVAC servicing, appliance replacement)
- Medical and dental out-of-pocket costs
- Annual insurance premiums
- Holiday gifts and travel
- Vacations or planned trips
- Back-to-school supplies
For each category, estimate the total cost and divide by the number of months between now and when you'll need it. That monthly figure becomes a fixed contribution — just like a bill — that you transfer to a dedicated savings space every pay cycle.
Start With Your Top Three Stress Expenses
Don't try to build a sinking fund for every category at once. Identify the two or three irregular expenses that have caused the most budget disruption in the past year and start there. Once those feel covered, add new categories gradually. Small wins build momentum.
The key habit shift is treating sinking fund contributions as non-negotiable monthly expenses, not optional savings. If you skip a month, you'll face a shortfall when the bill arrives. Automating transfers on payday makes this nearly effortless.
For more on finding room in your cash flow to fund these categories, the monthly budget audit checklist offers a practical starting point.
Sinking Funds vs. Emergency Funds: Know the Difference
A common point of confusion is treating sinking funds and emergency funds as interchangeable. They aren't. Your emergency fund is a financial safety net for genuinely unpredictable events — sudden job loss, an unexpected medical crisis, a car accident. It should not be earmarked for anything specific.
Sinking funds, by contrast, are for costs you fully expect. A tire replacement you've been postponing, a family reunion you've known about for six months, a dentist appointment you schedule every year — these belong in a sinking fund, not your emergency reserve. Using emergency savings for predictable costs leaves you exposed when a genuine crisis hits.
Sinking Funds Don't Require a Separate Bank Account
While a dedicated savings account makes sinking funds easier to track, some budgeters use a spreadsheet or budgeting app to 'earmark' portions of a single savings account to different categories. What matters most is that the money is mentally and practically set aside — not that it lives in a separate institution.
Think of them as two separate financial tools: an emergency fund is your airbag, and sinking funds are your routine maintenance budget. Both matter. Neither replaces the other.
Sinking funds are also a natural companion to travel planning. The habits that keep travel budgets on track often include setting up a dedicated vacation sinking fund months in advance.
The Link Between Sinking Funds and Financial Stress
Financial unpredictability is a well-documented source of stress. When you don't know how you'll pay for the next big bill, that uncertainty weighs on you — often before the expense even arrives. Sinking funds work partly because they convert financial uncertainty into a manageable routine.
When you know your car registration is already funded, it stops being a threat and becomes a transaction. That psychological shift — from dread to neutrality — compounds over time. Readers exploring the relationship between money and mental health may find the broader mental well-being resources useful alongside practical financial strategies.
For a deeper look at specific sinking fund categories and how to prioritize them, sinking funds explained in buckets walks through real-world allocation strategies.
This article is for general informational purposes only and does not constitute personalized financial advice. Consult a qualified financial professional for guidance specific to your situation.
Frequently Asked Questions

Finance Editorial Team
Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile