
Emergency Funds: Why Financial Experts Treat Them as Non-Negotiable
Learn what an emergency fund actually is, how much is generally recommended, and why it's considered the foundation of personal financial stability.
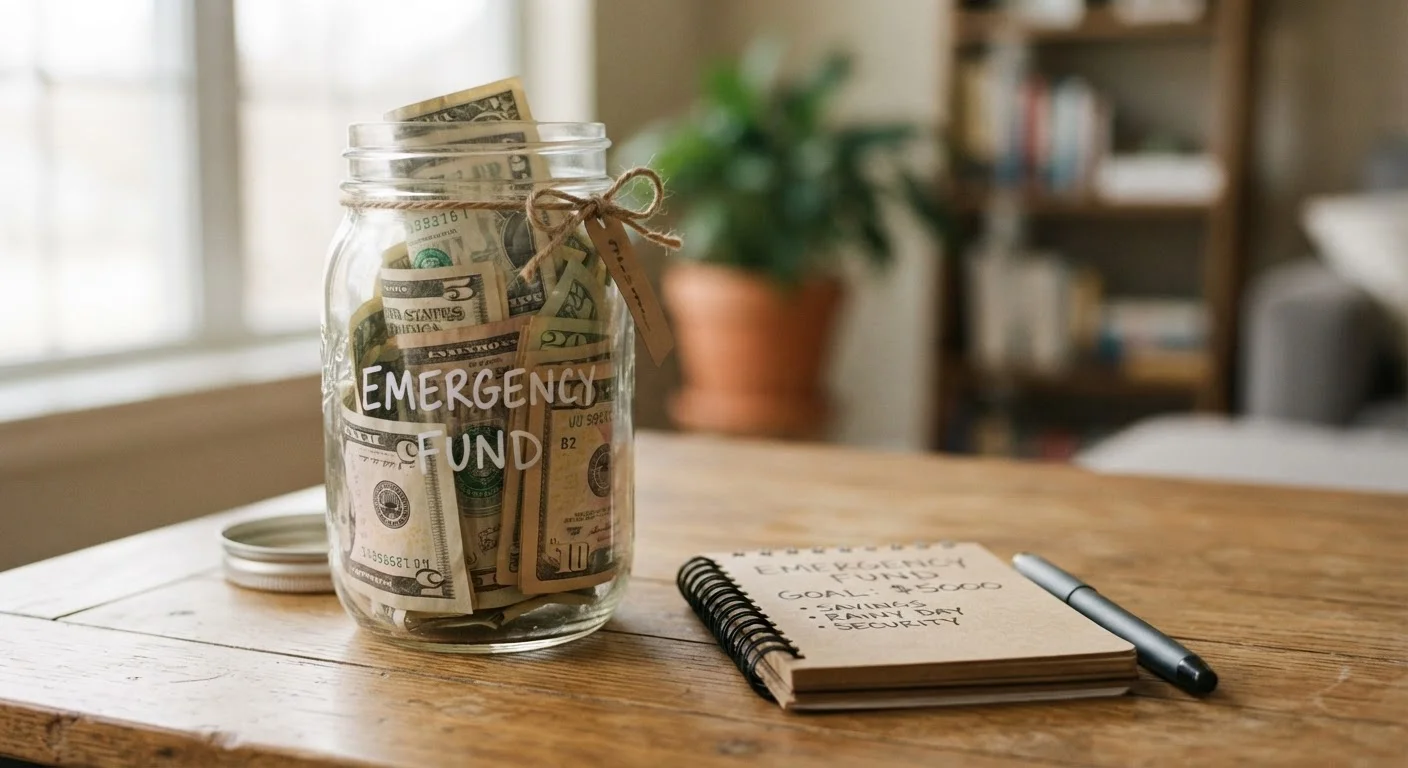
Photo: HorizonMetric.com | One Destination For Everyday Insights editorial
—— In This Article
Key Takeaways
- An emergency fund is savings reserved only for true, unplanned financial emergencies.
- Most financial guidance suggests saving three to six months of essential living expenses.
- Carrying debt does not disqualify you from needing or building an emergency fund.
- Without one, even a minor setback can force costly high-interest borrowing.
- Starting small — even $500 to $1,000 — provides meaningful protection while you build further.
What Makes Something a True Emergency
The word "emergency" gets stretched in everyday conversation, but in personal finance it has a specific meaning: an expense that is unexpected, necessary, and cannot be deferred. A leaking roof in winter, an emergency room visit, or income lost during an unexpected layoff all qualify. A sale on furniture or a spontaneous weekend trip does not.
This distinction matters because an emergency fund only works if it stays intact until it is genuinely needed. Raiding it for discretionary spending undermines the entire purpose — leaving you exposed when a real crisis arrives. Before building one, it helps to get clear on what your personal definition of an emergency actually is.
If you're unsure how to categorize irregular but predictable expenses like annual car registration or holiday costs, those are better handled with a different tool. See how sinking funds work for known future expenses — they serve a distinct purpose from an emergency reserve.
Why Three to Six Months Is the Standard Benchmark
The three-to-six-month guideline has become a widely cited reference point in personal finance education. The logic is straightforward: if you lost your primary source of income today, how long would it realistically take to replace it? That estimate — multiplied by your monthly essential costs — gives you a reasonable savings target.
Essential costs include housing, utilities, groceries, insurance premiums, and minimum debt payments. It does not include dining out, subscriptions, or other discretionary spending you could pause in a crisis.
~57%
Americans unable to cover a $1,000 emergency from savings
According to a Bankrate survey, a majority of U.S. adults say they could not pay for a $1,000 emergency expense using savings alone.
3–6 months
Recommended months of expenses in an emergency fund
This range is consistently cited by financial educators and nonprofit organizations as the broadly appropriate target for most households.
$1,000
Common recommended starter emergency fund target
Many personal finance educators suggest an initial goal of $1,000 as a meaningful buffer before tackling other financial priorities.
Someone with highly stable employment, no dependents, and low fixed expenses may feel comfortable at the lower end of that range. A freelancer, a single parent, or someone in a specialized field where job searches take longer may want to aim closer to six months or beyond. Neither choice is universally right — what matters is honest self-assessment.
If thinking through these tradeoffs sounds familiar, it's one of the core challenges covered in saving for multiple goals at once, which addresses how to balance an emergency fund alongside debt repayment and retirement saving.
Building One Even When Money Is Tight
One of the most common objections to emergency fund advice is the assumption that it only applies to people who already have extra money sitting around. In reality, the people with the least financial margin are often the most exposed to emergencies — and therefore have the most to gain from even a modest buffer.
Starting with a smaller, achievable target — often cited as $500 to $1,000 — creates a real layer of protection without requiring a complete financial overhaul. That amount covers many common emergencies: a car repair, an unexpected medical co-pay, a utility bill spike. Once that baseline is established, contributions can grow gradually alongside other financial goals.
Automate Even a Small Contribution
Setting up an automatic transfer — even $25 or $50 per paycheck — into a separate savings account removes the decision from your weekly routine. You're far more likely to build the fund consistently if it happens without active effort. Treat it like a recurring bill you pay yourself first.
Building this habit from scratch is entirely possible on a modest income. The foundational concepts are spelled out in building a savings habit from zero, which walks through realistic first steps for anyone who has never saved consistently before. And if you're still working on understanding your overall cash flow, personal budgeting from the ground up provides a solid starting framework.
The Real Cost of Skipping an Emergency Fund
Without a cash reserve, an unplanned expense typically gets absorbed one of two ways: by going into debt or by abandoning another financial goal. Both outcomes have lasting consequences.
Borrowing to cover an emergency — especially on a high-interest credit card — means paying considerably more than the original expense. A $1,200 car repair carried on a card charging 24% APR costs significantly more over time if only minimum payments are made. It also delays any progress toward debt payoff, savings, or investing goals.
“Before you invest a single dollar in the market, make sure you have a cash cushion you can access without touching your investments. The emergency fund isn't just a financial tool — it's the foundation everything else rests on.”
— Vanguard Financial Education Team, Financial education resource published by a major U.S. investment organization
The emergency fund essentially functions as a circuit breaker for your financial life. Without it, a single bad month can set off a chain reaction that takes years to reverse. Once one is in place, it also changes the psychological relationship with money — creating the kind of stability that makes longer-term planning feel less abstract. That stability is the bridge between managing today's expenses and eventually building toward goals like investing, covered in more depth in the Investing Essentials hub.
This article is for general informational and educational purposes only and does not constitute personalized financial advice. Consult a qualified financial professional for guidance specific to your situation.
Frequently Asked Questions

Finance Editorial Team
Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile