
Building a Savings Habit From Zero: A Practical Starting Point
Never saved consistently before? This guide explains the core concepts and realistic first steps for anyone starting a savings habit from scratch.
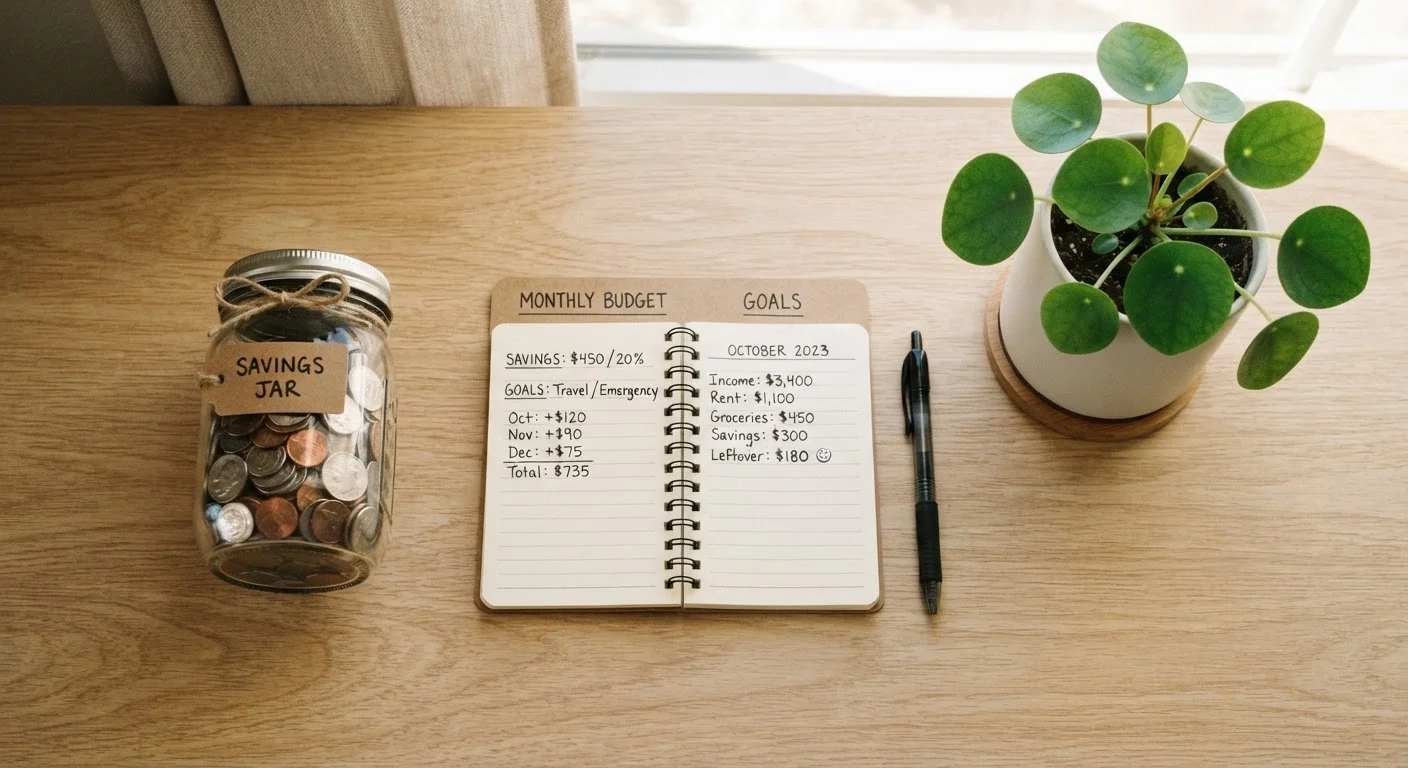
Photo: HorizonMetric.com | One Destination For Everyday Insights editorial
—— In This Article
Key Takeaways
- Even very small, consistent contributions build a meaningful savings habit over time.
- An emergency fund of three to six months of expenses is a widely recognized first savings goal.
- Automating transfers removes the temptation to skip saving when money feels tight.
- Carrying debt doesn't automatically mean you should stop saving — both goals can coexist with structure.
- Where you keep savings matters: accounts with higher interest rates let your money work harder.
Why Starting From Zero Is Normal
Many Americans reach adulthood without ever being taught a practical savings method. If you have no savings right now — or if previous attempts haven't stuck — that reflects a gap in financial education, not a personal failure. According to Federal Reserve survey data, a meaningful share of U.S. households report they would struggle to cover a $400 unexpected expense from savings alone, which shows how widespread this starting point actually is.
The good news: building a savings habit is a learnable skill, not an innate trait. It starts with understanding a few foundational concepts, then taking one small, concrete action. Before diving in, it also helps to know where savings fits within your broader money picture. If you haven't yet mapped out your income and expenses, our introduction to personal budgeting covers the ground that comes just before saving.
Core Concepts Every New Saver Should Know
Emergency Fund
A savings reserve set aside exclusively for unexpected essential expenses — job loss, medical bills, or urgent repairs. It prevents unplanned costs from becoming new debt.
Compound Interest
Interest calculated on both your original deposit and any interest already earned. Over time, this causes a balance to grow faster than simple interest would.
Automated Transfer
A scheduled, recurring movement of money between accounts — typically from checking to savings — that happens without any manual action each time.
Liquid Savings
Money held in accounts you can access quickly and without penalty, such as a savings account. Keeps funds available for emergencies without locking them up.
Sinking Fund
A savings method where you set aside a fixed amount regularly for a known future expense, so the cost doesn't hit your budget all at once.
Understanding these terms helps you make sense of savings advice without feeling lost. Two concepts deserve special attention for beginners: the emergency fund and compound interest.
An emergency fund is your first savings priority because it acts as a financial buffer, preventing a car repair or medical bill from derailing your budget entirely. Without one, unexpected costs often end up on a credit card, creating new debt.
Compound interest works in your favor over time — interest earned on your balance is added to that balance, so future interest is calculated on a larger amount. The longer money sits in an account earning interest, the more noticeably this effect compounds. Our article on how compound interest builds long-term wealth explains this mechanic in depth.
Your First Realistic Steps
Starting a savings habit doesn't require a complete financial overhaul. These four steps create a workable foundation:
- Open a dedicated savings account. Keeping savings separate from your checking account reduces the temptation to spend it. Accounts that offer a higher interest rate — often called high-yield savings accounts — let your balance grow faster without any extra effort. See our comparison of high-yield and traditional savings accounts for a clear breakdown of the differences.
- Set one specific, small goal. Rather than a vague intention to "save more," pick a number — even $250 or $500 — as your initial emergency fund target. A concrete goal gives you something to work toward and a moment to celebrate when you reach it.
- Automate the transfer. Set up a recurring transfer from checking to savings on payday, even if it's only $20. Automation sidesteps willpower entirely. Our guide on automating your finances explains the psychology behind why this works so reliably.
- Build your budget first, then save what's left. Use a step-by-step monthly budget to understand your actual spending before deciding on a transfer amount. Saving what's left without a budget often results in saving nothing.
Start With One Month's Buffer
Before targeting a full three-to-six-month emergency fund, aim for just one month of essential expenses. This smaller milestone is achievable faster and immediately provides real financial protection. Once you hit it, extend the goal from there.
Saving When You're Also Carrying Debt
Debt and saving feel like opposites, but most households need to manage both at the same time. The practical question is: how much of each?
A commonly used framework suggests building a small emergency fund first — often cited as around $1,000 — before aggressively paying down debt. The reasoning: without any savings buffer, a single unexpected expense sends you right back to borrowing. Once that cushion exists, direct extra money toward high-interest debt until it's eliminated, then build savings further.
Not every situation fits a single framework, though. Interest rates, income stability, and the types of debt involved all affect the right balance. For a structured way to think through these tradeoffs, our article on saving while in debt walks through the considerations clearly.
This Is General Education, Not Personal Advice
The frameworks described here are widely used starting points, not prescriptions for any individual situation. Factors like your specific debt interest rates, income stability, and household needs all affect the right approach for you. A licensed financial professional can help you weigh these variables based on your actual circumstances.
Once you've stabilized savings and reduced debt, structured saving for known future costs — car registration, annual insurance premiums, holiday spending — becomes the next useful layer. That approach is called a sinking fund; see sinking funds explained for how it works.
Building the Habit So It Sticks
The biggest obstacle to saving consistently isn't usually income — it's inconsistency. Habits take repetition to solidify, and savings is no different.
A few practices that support long-term consistency:
- Review your savings balance monthly. Seeing growth, even small growth, reinforces the behavior. What gets measured gets attention.
- Increase your transfer gradually. Each time your income increases — a raise, a side income, a paid-off loan — redirect a portion to savings before adjusting your lifestyle spending.
- Don't treat a missed month as failure. Skipping a transfer during a genuinely tight month is a setback, not the end. Reset and continue the next pay cycle.
- Keep the long view in mind. Once your emergency fund is solid and high-interest debt is managed, the natural next step is putting savings to work through investing. The beginner's guide to investing is a logical next read when you're ready for that transition.
This article is for general informational and educational purposes only. It does not constitute personalized financial, tax, investment, or legal advice. Consult a qualified financial professional before making decisions specific to your circumstances.
Frequently Asked Questions

Finance Editorial Team
Finance Editorial Team is the collective byline for our editorial team and contributor network. Articles published under this byline or an editorial pen name are researched, written, and reviewed according to our editorial standards for clarity, consistency, and independence before publication.
View author profile